Dock Builder Insurance: How Waterfront Construction Affects Coverage Needs
October 8, 2026
“Dock builder” sounds like a single job or trade, but the label covers a wide range of waterfront work. You’re a dock builder if you install floating residential docks from the shoreline of an inland lake, but also if you drive piles from a barge-mounted crane to build a commercial pier in a busy harbor.
Given the varying risks, dock builder insurance built around a generic job description can result in coverage gaps or unnecessary coverage. If you’re working with dock builders, start with a clear picture of what the contractor builds, where the crew works, what equipment it uses, and who actually performs the work.
What Can Change a Dock Builder’s Insurance Needs?
Operational details are often what shape a dock builder’s risk profile. Here are five factors that can affect insurance needs.
Structure Type
A contractor that assembles floating docks and installs boat lifts for homeowners faces a different set of risks than one that builds fixed timber piers, bulkheads, seawalls, or full marina facilities. Larger and more permanent structures raise the stakes for completed operations claims. Repair and replacement work often puts the contractor in close contact with a customer’s existing structures, boats, and shoreline property.
Where the Work Happens
A crew working from the shore on a small private lake operates in a different environment than one working on tidal water, in a commercial harbor, or near a port. Location can determine which liability forms fit, whether federal workers’ compensation rules apply, and what coverages a project owner will demand. Municipal and port projects frequently include specific insurance requirements in the contract.
Vessels, Barges, Canes, and Other Equipment
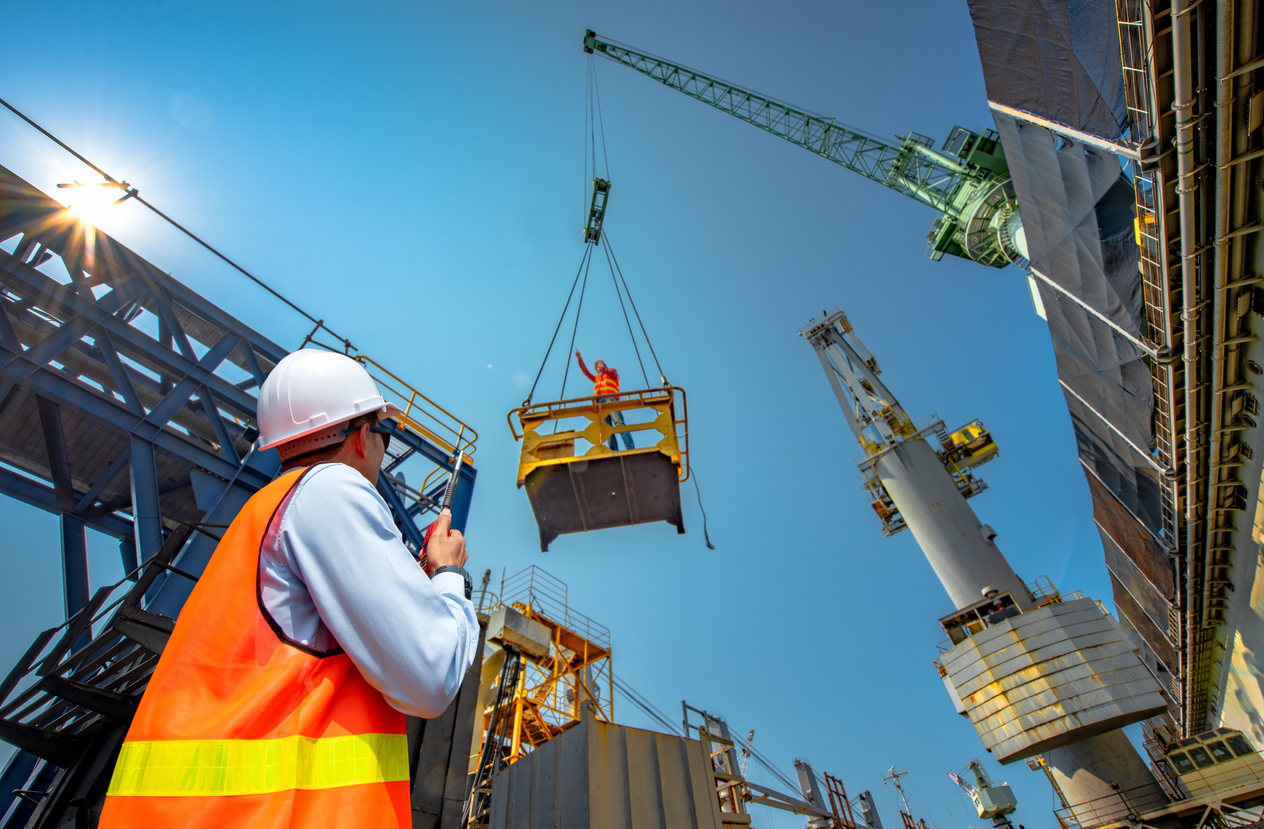
Some dock builders never put a vessel in the water. Others run workboats, push boats, spud barges, or crane barges every day. Once a contractor owns or operates watercraft, the account picks up vessel-related property and liability exposures. Equipment that travels by water or works from a floating platform also faces perils that a standard land-based equipment policy may not contemplate.
Employee Responsibilities
Job titles don’t tell you much about a waterfront crew. You need to know who works over or beside the water, who works only on land, and who operates or crews the company’s vessels. Those duties can determine which compensation system responds when someone gets injured.
Subcontracted Work
Many dock builders hire out specialized tasks such as diving, underwater inspection, welding, crane service, or pile driving. Subcontractors bring their own exposures onto the job site that need to be accounted for.
How Operations Affect Coverage
A dock builder doesn’t automatically need every marine coverage. The operations you uncover should point you toward the policies that are actually relevant.
Marine General Liability
Most dock builders need liability protection for bodily injury and property damage tied to their work. Marine general liability can include products and completed operations coverage for work performed from watercraft, which standard commercial general liability forms may exclude. A contractor who works from boats or barges or near navigable water usually needs this marine form.
Marine Contractors Liability
This coverage addresses property damage to the marine structures that a contractor works on or around. This coverage is especially important for contractors who repair, extend, or replace existing docks, piers, and bulkheads, where a mistake can damage the customer’s property or a neighbor’s.
Hull and P&I
When a dock builder owns or operates workboats or barges, hull coverage protects against physical damage to the vessels. Protection and indemnity (P&I) coverage responds to legal liability arising from vessel operations, such as collisions, damage to docks, or injuries to people aboard.
Contractor’s Equipment With Waterborne Coverage
Cranes, pile drivers, excavators, and generators represent a major investment for many dock builders. Contractor’s equipment (inland marine) coverage with a waterborne extension can protect equipment while it sits on a barge or moves across the water to a job site.
USL&H
The Longshore and Harbor Workers’ Compensation Act (LHWCA) is a federal law that provides specialized workers’ compensation insurance for maritime employees. Your client may need longshore coverage, which depends on a business’s operations, location, and case law.
What Should Agents Clarify Before Submission?
A complete submission helps a marine underwriter understand the account quickly and price it accurately. Some of the important details to collect from your client include:
- Scope of work: What types of structures does the contractor build, repair, or remove? Break out the mix of residential, commercial, and municipal work, and note the largest contract the company has completed or expects to take on.
- Project locations: Which bodies of water and states does the contractor work in? Note whether the work takes place on inland lakes, rivers, tidal water, or in harbors and ports.
- Vessels and equipment: List any owned, leased, or chartered workboats and barges, along with their lengths, values, and operators. Schedule major equipment, and note which pieces work from the water.
- Employees: Find out how many people work over or adjacent to the water, how many stay on land, and who serves as vessel crew. Payroll by duty helps the underwriter sort out USL&H and Jones Act exposures.
- Subcontractors: Identify which tasks the contractor hires out, whether subcontractors provide certificates of insurance, and whether contracts require them to name the contractor as an additional insured.
Build the Coverage Around the Work
Two dock builders can share a job title and still need distinct insurance programs. The structures they build, the water they work on, the vessels and equipment they run, the duties their employees perform, and the subcontractors they hire should all guide the coverage discussion.
Merrimac Marine Insurance works with agents every day to structure coverage for dock builders and other marine contractors. Reach out today to talk through your client’s operations with one of our marine specialists.
About Merrimac Marine Insurance
At Merrimac Marine, we are dedicated to providing insurance for the marine industry to protect your clients’ businesses and assets. For more information about our products and programs, contact our specialists today at (800) 681-1998.