Marine Liability Insurance Coverage for Marinas: Which Coverages Apply to Different Operations?
September 15, 2026
A marina may do far more than provide dockage or storage. Some also rent or sell boats, perform repairs, or operate restaurants, shops, and other businesses. Marine liability insurance coverage needs to account for the full scope of those operations.
For agents, the first step is understanding exactly what the marina does. Each added service can introduce distinct liability exposures that require careful attention.
What Boat-Related Operations Does It Perform?
Storing, renting, and selling vessels create different exposures because the marina’s responsibility for the boat, the customer, and the surrounding property changes with each activity.
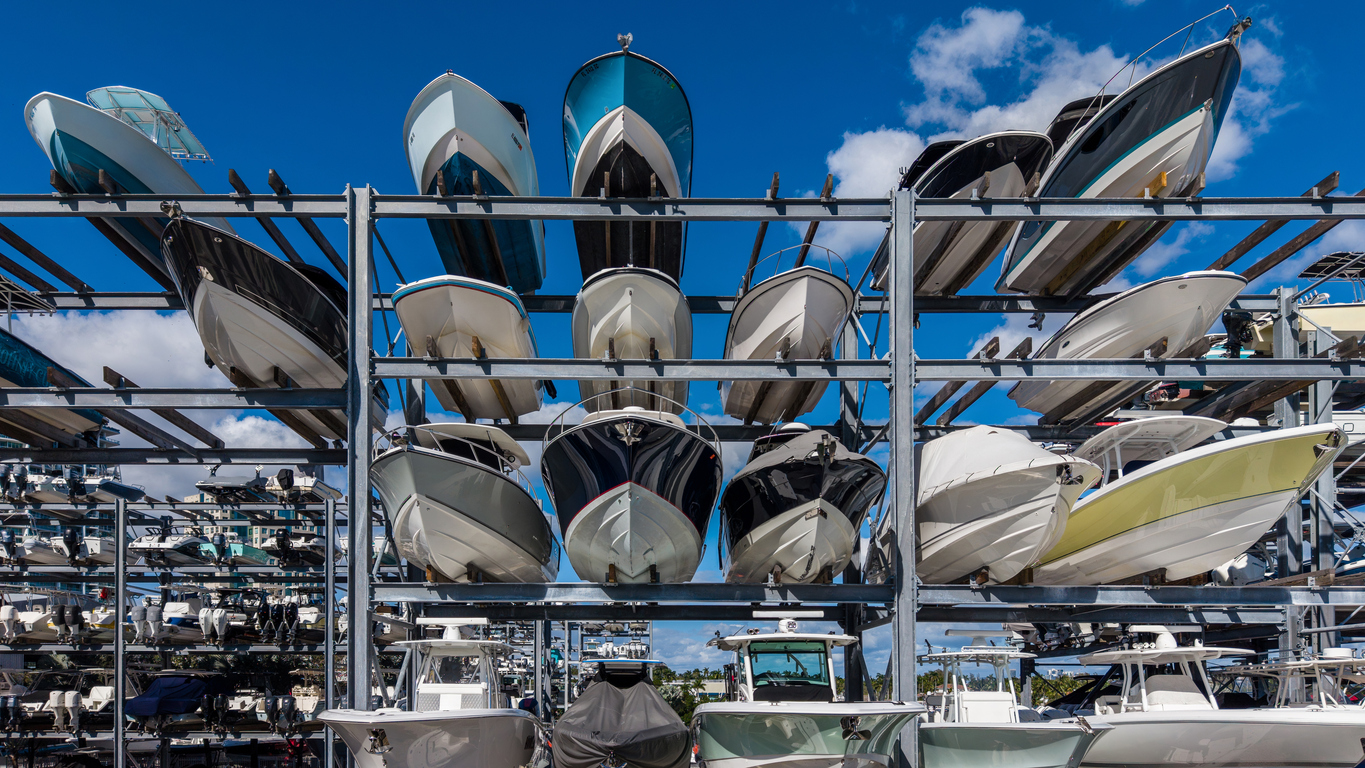
A marina that stores customer vessels is responsible for property belonging to others while it is in the marina’s care, custody, or control — an exposure addressed by marina operators legal liability coverage. Add rentals, and the marina is putting customers aboard its own vessels on the water. Add sales, and inventory, demonstrations, and other dealer-related exposures come into play.
Those differences can change which liability coverages deserve attention. A marina devoted primarily to storage presents a different risk profile from one that also rents or sells watercraft. Agents should evaluate the operation as it exists today rather than rely on a standard marina package.
That review can be especially important as insurance costs rise. Pressure to control premiums should not come at the expense of overlooking exposures created by the marina’s operations.
Does It Perform Repairs or Services?
Does the marina repair or service boats? If so, what kind of work does it perform, and what exposure remains after the job is finished? A yard focused on bottom painting and winterization presents a different risk from one handling repowers or structural repairs. In either case, employees are working on customer vessels, creating potential liability exposures while the work is underway and after it has been completed.
Two coverages may warrant a closer look: ship repairers legal liability and products-completed operations liability. Which applies, and how, depends on the work being performed and the policy terms.
What Other Businesses Operate On-Site?
Sometimes a marina isn’t just one business but multiple businesses. Restaurants, ship’s stores, fuel docks, event lawns, and lodging all can turn up at marinas, and they carry exposures that have nothing to do with boats. Food service, retail transactions, and public gatherings bring people onto the property who never touch a vessel.
These risks belong in the placement and renewal conversation, even though they sit outside the marine label. The marina’s business classification alone may not capture every exposure.
Look Beyond the Marina Label
Assume no two marina accounts are alike until the operations say otherwise. Walk through the boat-related activities, the repair and service work, and the ancillary businesses before deciding which liability considerations deserve attention — rather than assuming all marinas present the same liability profile. Explore our website for additional marine insurance resources, and contact Merrimac Marine Insurance for further assistance with your marina clients.
About Merrimac Marine Insurance
At Merrimac Marine, we are dedicated to providing insurance for the marine industry to protect your clients’ businesses and assets. For more information about our products and programs, contact our specialists today at (800) 681-1998.